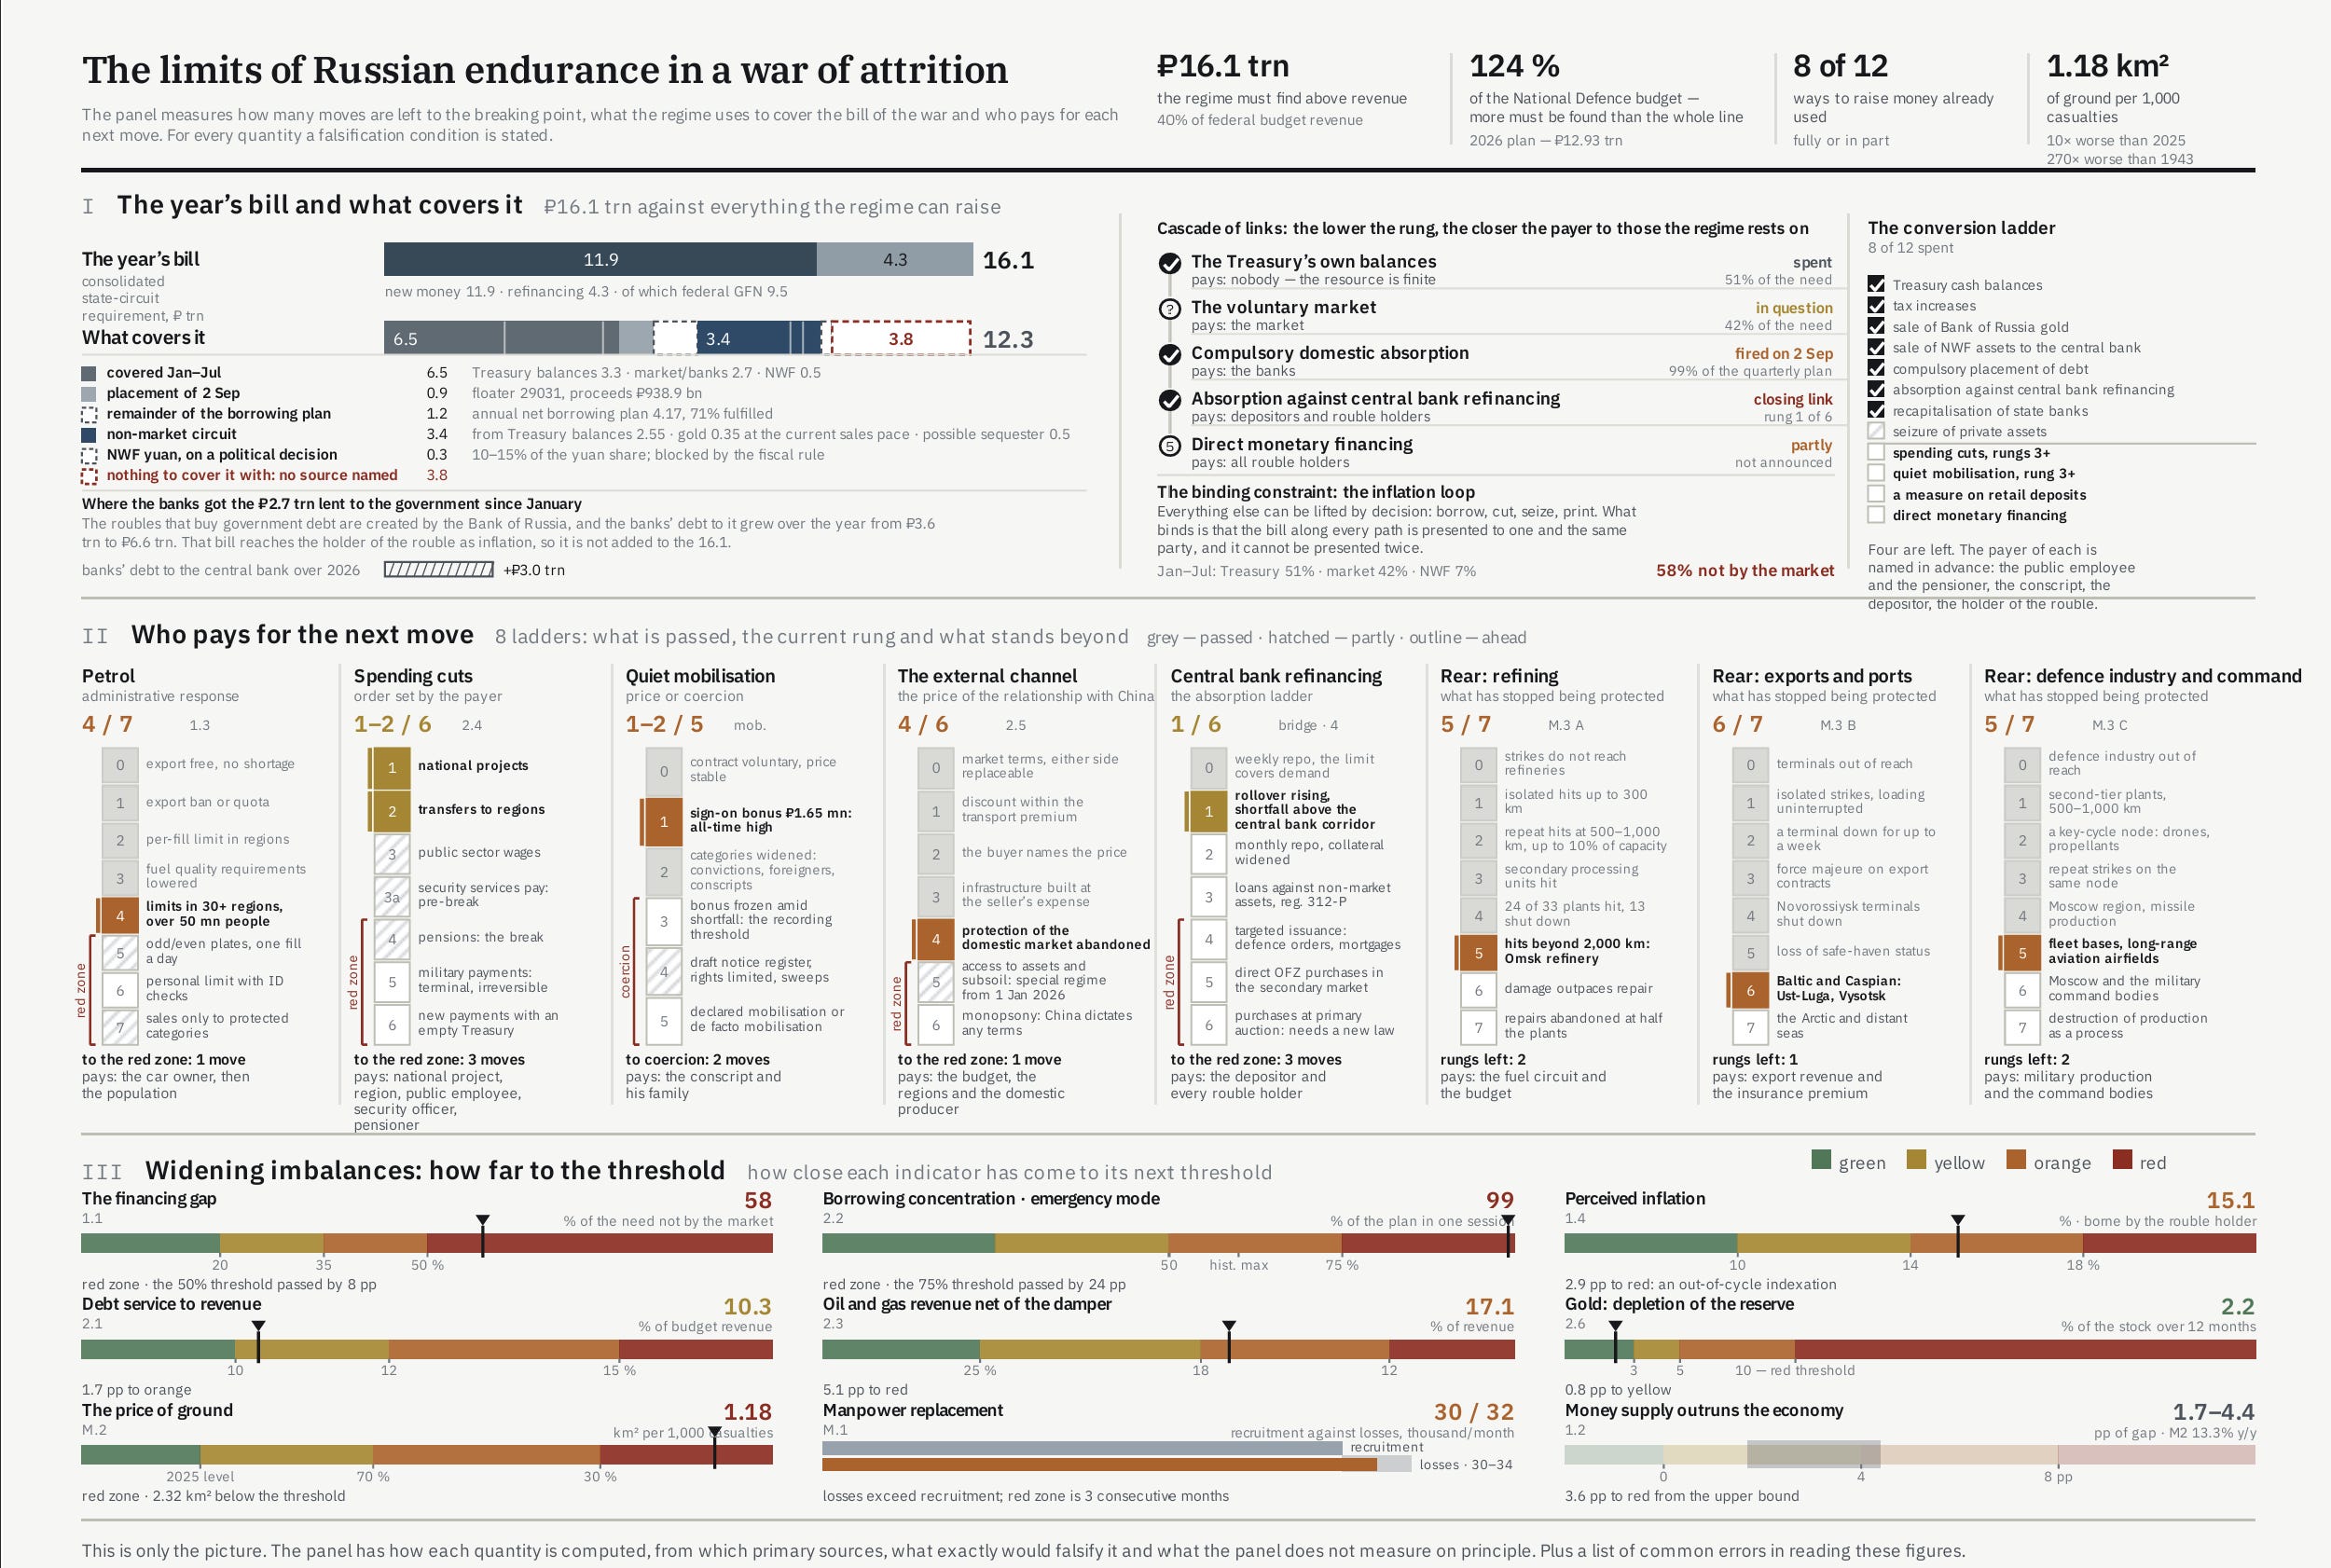
Version 2.0 of the panel is out today in English, Ukrainian and Russian, with a new gold widget, three widgets run again on 12 September once the OFZ auctions came back, and a summary table redrawn so that every indicator shows how far it still stands from its next threshold; for readers who would rather pass a file than a link, the full panel is also out as a PDF, in all three languages.
The bill for 2026 is ₽16.1 trn above revenue, 124% of the entire National Defence line. Over January to July, 58% of what had to be financed was closed outside the market, 51 points of it from Treasury balances = more than half of seven months’ financing came out of money already sitting on the Treasury account. When the “market” reopened on 2 September, after 63 days without a single completed placement, it gave 99% of the quarter’s borrowing in one session. In 2022, 2024 and 2025 this emergency mode came in November and December. This year it came in September.
In the second quarter the Bank of Russia was the only central bank selling gold in any real volume, 21.77 t against 4.23 t for the next seller, and it did so in a quarter when the official sector as a whole bought 289 t, more than in any second quarter on record. In 2025 it sold 6 t: a small number, but the first time in twenty years the stock went down over a full year. In the first seven months of 2026 it sold 49.7 t.
Every other conversion mechanism on the panel has a ceiling the Kremlin sets for itself; the ceiling on gold is set in Beijing, New Delhi and Ankara.